Flood zone
X or AE can swing it thousands.
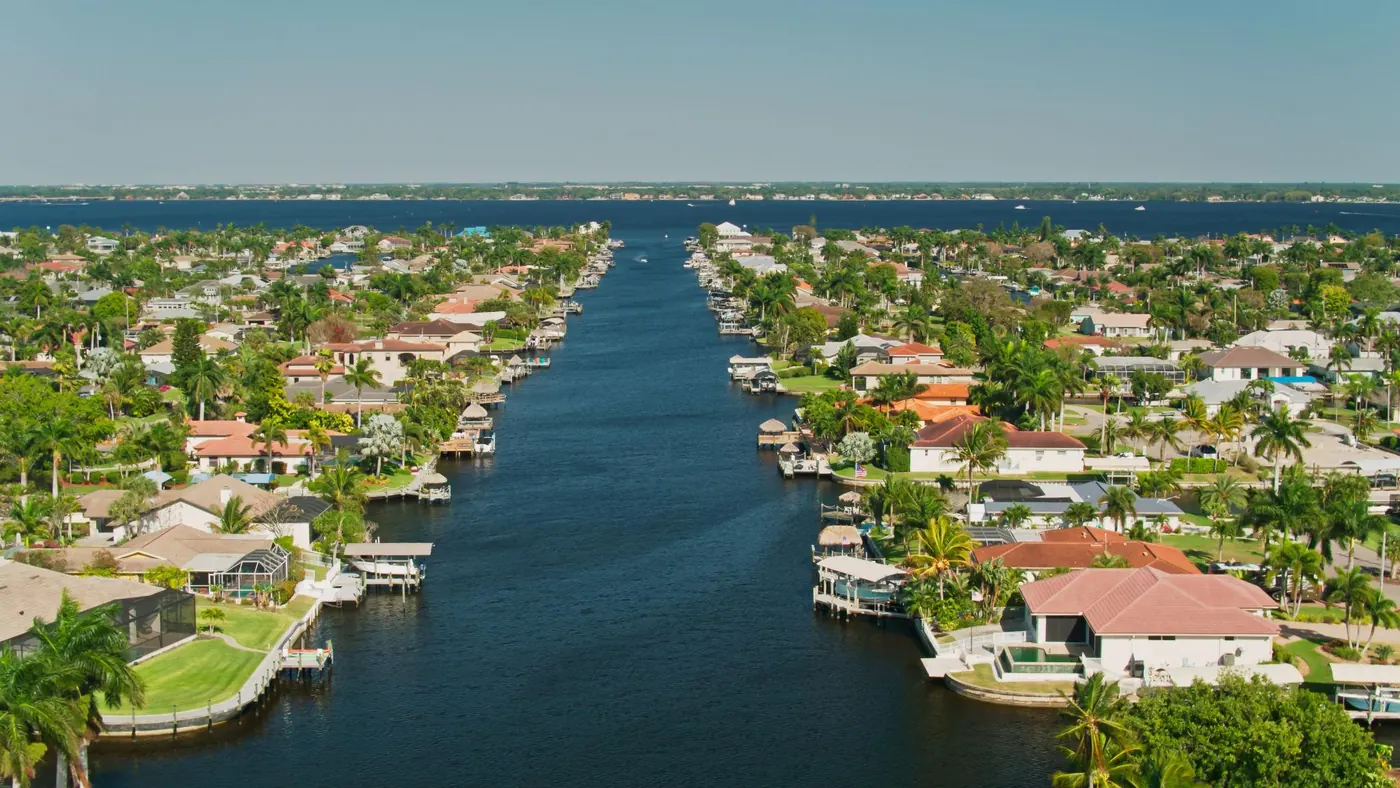
Two homes on the same street can sit in different zones. We pull the flood zone and elevation certificate on every home before you fall in love with it.
Most calculators stop at the mortgage. Here, the stuff that actually changes your number in Southwest Florida is built in: homestead, your flood zone, insurance on a new build versus an older home, HOA, utility assessments and upkeep. Slide things around and watch it move.
The four things we walk every buyer through before they write an offer here.
Two homes on the same street can sit in different zones. We pull the flood zone and elevation certificate on every home before you fall in love with it.
A new roof, impact windows and current code earn real credits. On an older home, a wind mitigation inspection is the cheapest way to bring the premium down.
Homestead lowers the taxable value and caps increases at 3% a year. Without it, a second home is taxed on the full value and most of the bill can rise up to 10% a year.
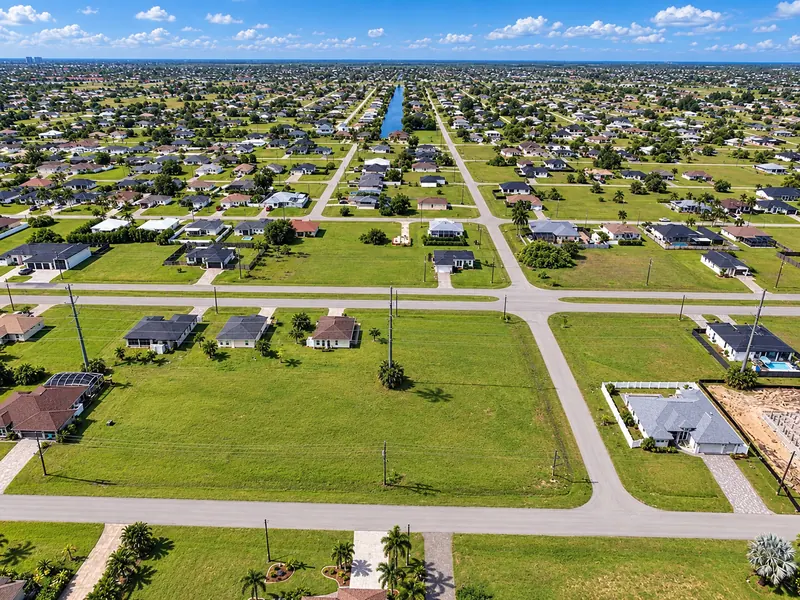
Parts of the north Cape are still getting city water and sewer. That assessment rides on the tax bill for years, so it belongs in the budget from day one.
What buyers ask us most once they see the full monthly cost.
Cape Coral's combined millage is roughly 14.4 mills, about $14.40 for every $1,000 of taxable value, plus roughly $900 to $1,100 a year in city fees for fire, stormwater and trash. Homestead on a primary home takes up to $50,000 off the taxable value and caps future increases at 3% a year. Without homestead, you're taxed on the full assessed value.
In an AE or VE zone with a mortgage, your lender will require it. In X and X500 it's optional, but it's usually a few hundred dollars a year and most of our clients carry it anyway. Ask whether the seller's NFIP policy can transfer to you, because that can save real money.
Usually, yes. A new roof, impact protection and the current building code earn better homeowners rates and wind mitigation credits. New homes built above the base flood elevation often see much lower flood premiums too. That's a real part of the math when you're comparing a new build to an older home at the same price.
The Utilities Extension Project brings city water, sewer and irrigation to areas of Cape Coral still on well and septic. Owners in those areas get an assessment that can be paid off or financed on the tax bill for 20 to 30 years. Recent North Cape projects have run several thousand dollars a year when financed, so we always check before you buy.
Send us an address and we'll pull the actual taxes, flood zone and any assessments, then plug in real insurance quotes.